Arthur Cecil Pigou succeeded Prof. Marshall as the Professor of Economics at the University of Cambridge. After Marshall, he became the leading neo classical economist. He is the founder of “Welfare Economics” His leading ideas on welfare economics are found in his “Economics of Welfare” (1920)..
People also ask, who is the father of economics?
Adam Smith
Subsequently, question is, what is theory of welfare economics? Welfare economics is a branch of economics that uses microeconomic techniques to evaluate well-being (welfare) at the aggregate (economy-wide) level. Because of welfare economics' close ties to social choice theory, Arrow's impossibility theorem is sometimes listed as a third fundamental theorem.
Just so, why pigeon is called the father of welfare economics?
Pigou regard economic welfare and national income as essentially coordinate. It is on this basis that he lays down two conditions for maximisation of welfare. The first condition states that welfare is said to increase when national income increases.
What is meant by welfare economics?
Welfare economics is defined as a branch of economics that studies how the distribution of income, resources and goods affects the economic well-being. An example of welfare economics is the study of how certain health services help bridge the barrier between different classes of people.
Related Question Answers
What are the three laws of economics?
To discover and elaborate three rulesConsumption and Management discovers and elaborates three rules: natural economic law, market regulation law, and the law of macro-economic control. The developing process of currency produces the economic law of financial enterprise and the law of natural (free) market economy.What are the 3 economic theories?
Three Competing Theories. The three competing theories for economic contractions are: 1) the Keynesian, 2) the Friedmanite, and 3) the Fisherian. The Keynesian view is that normal economic contractions are caused by an insufficiency of aggregate demand (or total spending).Who created capitalism?
Adam Smith
Who coined the word economics?
The English term 'Economics' is derived from the Greek word 'Oikonomia'. Its meaning is 'household management'. Economics was first read in ancient Greece. Aristotle, the Greek Philosopher termed Economics as a science of 'household management'.Who was the first economist?
1. Adam Smith (1723-1790) Adam Smith was a Scottish philosopher who became a political economist in the midst of the Scottish Enlightenment. He is best known for The Theory of Moral Sentiments (1759) and An Inquiry into the Nature and Causes of the Wealth of Nations (1776).Who is the mother of economics?
WHEN NOBEL prize winner Amartya Sen is invested with the Jewel of India at a glittering ceremony before the country's president, prime minister and cabinet, and broadcast live on television, it will complete the apotheosis of the man dubbed the "Mother Teresa of Economics".Who is Indian Economic father?
P.V. Narasimha Rao was part of Vande Matram movement in late 1930s in the Hyderabad state.What was Adam Smith's economic theory?
Adam Smith's theory is based on the principle of 'Laissez-Faire' which requires that state should not impose any restriction on freedom of an individual. The theory of economic development rests on the pillars of saving, division of labour and wide extent of market.Why do we study economics?
Economics is the study of how societies use scarce resources to produce valuable commodities and distribute them among different people. Indeed, economics is an important subject because of the fact of scarcity and the desire for efficiency.What is welfare gain?
Net welfare gain – definition. A net welfare gain refers to the impact of a government policy, or a decision by firms, on total economic welfare, taking into account the gains, less any losses.What is modern welfare approach?
Welfare state. Sociologist T. H. Marshall described the modern welfare state as a distinctive combination of democracy, welfare, and capitalism. As a type of mixed economy, the welfare state funds the governmental institutions for healthcare and education along with direct benefits given to individual citizens.Who gave welfare theory of economics?
It is reasonable to say that Adam Smith (1776) has played an important role in the development of welfare theory.What defines economic growth?
Economic growth is the increase in the market value of the goods and services produced by an economy over time. It is conventionally measured as the percent rate of increase in real gross domestic product, or real GDP. An increase in per capita income is referred to as intensive growth.What is optimality in economics?
From Wikipedia, the free encyclopedia. Pareto efficiency or Pareto optimality is a state of allocation of resources from which it is impossible to reallocate so as to make any one individual or preference criterion better off without making at least one individual or preference criterion worse off.What are the nature and scope of economics?
The nature and scope of economics are related to the study of wealth or human behaviour or of scarce resources. The scope is very wide and includes the subject matter of economics whether economics is a science or an art or whether it is positive or normative science.What is social indifference curve?
Definition. A social indifference curve consists of distributions of welfare of members of a group that the policy maker views as achieving the same social welfare.How does welfare impact the economy?
Overall, the strong economy has clearly helped reduce caseloads and increase work opportunities. It has also helped reduce poverty and raise income (primarily through increases in earnings) in poor families.What is Pareto efficient in economics?
What Is Pareto Efficiency? Pareto efficiency, or Pareto optimality, is an economic state where resources cannot be reallocated to make one individual better off without making at least one individual worse off.What is deadweight loss economics?
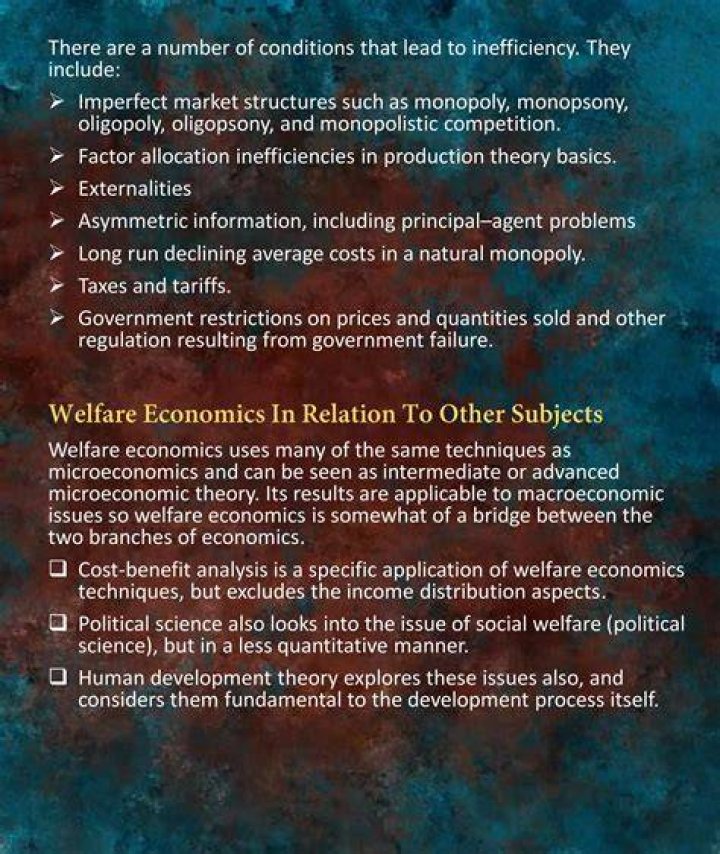
A deadweight loss, also known as excess burden or allocative inefficiency, is a loss of economic efficiency that can occur when the free market equilibrium for a good or a service is not achieved. 
 Isabella Browning