What is the difference between standard cost and average cost?
 Mia Ramsey
.
Moreover, what is the difference between standard cost and actual cost?
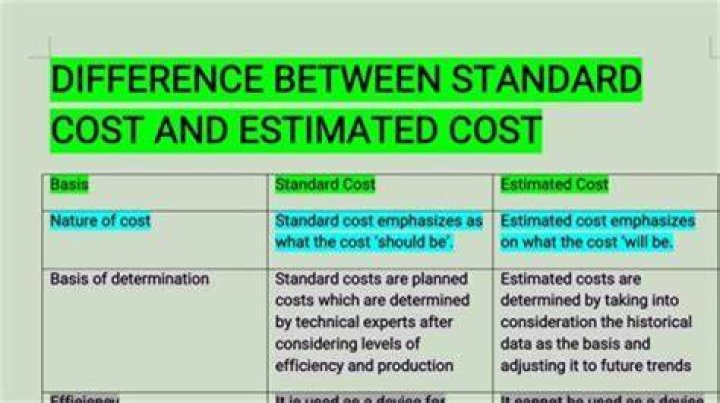
A standard cost is a pre-determined or pre-established cost to make a unit of finished product. Actual cost is the actual cost of direct materials, direct labor, and overhead to make a unit of product. The difference between actual cost and standard cost is called variance.
One may also ask, what does standard price mean? A uniform price that is pre-established for services or goods that is based on cost of replacement, historical prices or the analysis of it competitive market position.
Secondly, what is an ideal standard cost?
1. Ideal, Perfect, Maximum Efficiency or Theoretic Standards: Ideal standards (costs) are the standards which can be attained under the most favourable conditions possible.
What is a standard cost system?
In accounting, a standard costing system is a tool for planning budgets, managing and controlling costs, and evaluating cost management performance. A standard costing system involves estimating the required costs of a production process.
Related Question Answers
What are the types of standard costing?
Types of Standard Costs- The standard cost set could be basic, ideal, attainable or current.
- They can be revised periodically to reflect changes in the organizations operating conditions.
- However, since the ideal standards assume perfect operating conditions, they would be unattainable in real life, which has normal operating problems.
How is cost measured?
represent methods used to measure and record the cost of direct materials, direct labor, and factory overhead. There are three cost measurement methods: actual costing, normal costing, and standard costing.What is the purpose of using standard costs?
Standard Costing System. In accounting, a standard costing system is a tool for planning budgets, managing and controlling costs, and evaluating cost management performance. A standard costing system involves estimating the required costs of a production process.What is actual price?
Meaning of actual price in Englishthe price of a commodity (= a product such as oil, metal, grain, or coffee) that can be sold and delivered immediately: the actual price of sth To see the actual price of gold you have to look at what dealers are charging. See also. cash price.What is SAP actual cost?
Actual Costing is functionality provided by SAP to calculate actual prices i-e; PUP (periodic unit price) of inventories/ valuated material including Raw Material (ROH), Semi- Finished Good (HALB) and Finished Good (FERT). It includes all the actual prices for material in particular period.How do you set up a standard cost system?
The following steps are involved for establishing standard costing system in an organization.- Determination of Cost Centre.
- Classification of Accounts.
- Codification of Accounts.
- Setting of Standards.
- Establishing Standard Costs.
- Preparing Standard Cost card or Standard Cost Sheet.
- Organization for Standard Costing.
What are the limitations of standard costing?
Standard costing has certain limitations which are as follows : (1) Setting of standard is a very difficult task and it involves a high degree of technical skill. Therefore it is costly and will be expensive from the point of view of small concern. (2) Conditions of the business are charging.What are the 4 types of standards?
Standards in Accounting (4 Types)- Ideal, Perfect, Maximum Efficiency or Theoretic Standards:
- Normal Standards:
- Basic Standards:
- Currently Attainable or Expected Actual Standards:
What are basic standards?
Basic Standards are the unaltered standards which are used over for a longer period of time and do not reflect current conditions. These standards are not useful from the cost of control point of view as they consider only fixed costs.What are the different types of standard?
Following are different types of standards:- Basic standards.
- Normal standards.
- Current standards.
- Attainable (expected) standards.
- Ideal (theoretical) standards.
What are the three types of standards?
Following are different types of standards:- Basic standards.
- Normal standards.
- Current standards.
- Attainable (expected) standards.
- Ideal (theoretical) standards.
What expected standard?
expected standard. standard set at a level that reflects what. is actually expected to occur in the future period; it anticipates. future waste and inefficiencies and allows for them; is of limited value for control and performance evaluation purposes.What are current standards?
Current standards are standards which are established for use over a short period of time, and are related to current conditions. They represent current costs to be expected from efficient operations. These standards do not anticipate ideal performance; they are difficult, but possible to achieve.What are the two types of standards?
ASTM publishes six different types of standards: test method, specification, classification, practice, guide, and terminology.What are the disadvantages of standard costing?
The disadvantages include that implementing a standard costing system can be time consuming, labor intensive, and expensive. If the cost structure of the production process changes, the standards have to be updated.What is attainable standard?
December 5, 2018 by rashidjaved. Currently attainable standards are standard costs that are achievable by a specified level of effort and allow for normal spoilage, waste, and nonproductive time.What are some of the advantages and disadvantages of standard costs?
The primary advantages to using a standard costing system are that it can be used for product costing, for controlling costs, and for decision-making purposes. Whereas the disadvantages include that implementing a standard costing system can be time consuming, labor intensive, and expensive.What are different types of costs?
DIFFERENT WAYS TO CATEGORIZE COSTS- Fixed and Variable Costs.
- Direct and Indirect Costs.
- Product and Period Costs.
- Other Types of Costs.
- Controllable and Uncontrollable Costs—
- Out-of-pocket and Sunk Costs—
- Incremental and Opportunity Costs—
- Imputed Costs—