What does a deed in lieu do to your credit?
 Emily Cortez

.
Furthermore, how long does a deed in lieu affect your credit?
seven years
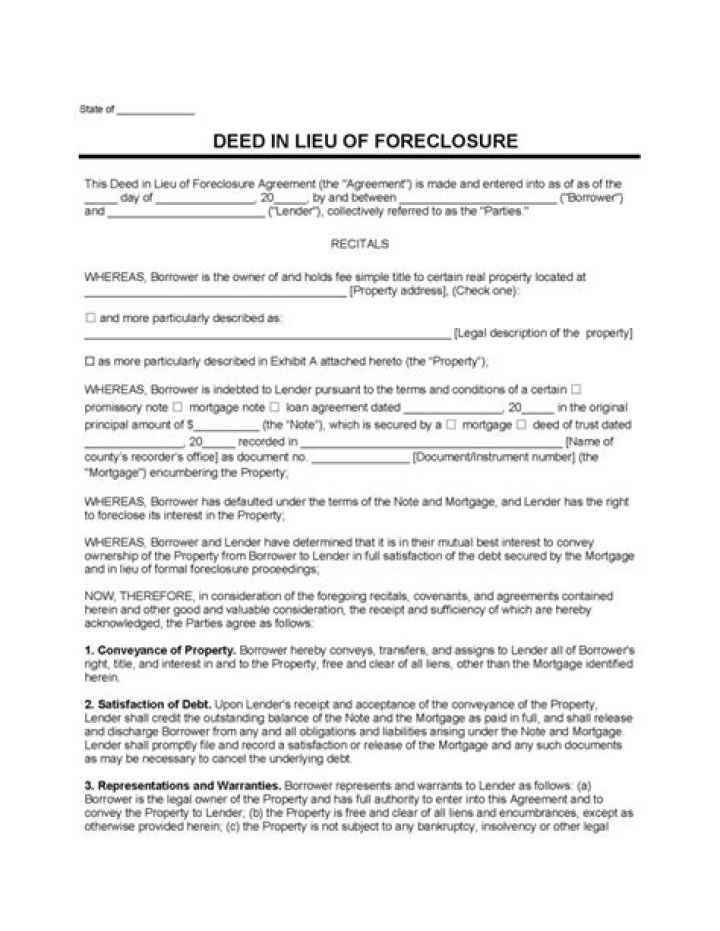
Likewise, how does a deed in lieu work? A deed in lieu of foreclosure is a transaction in which the homeowner voluntarily transfers title to the property to the bank in exchange for a release from the mortgage obligation. Generally, the bank will only approve a deed in lieu of foreclosure if there aren't any other liens on the property.
Also, how does deed in lieu show on credit report?
People can just let the home go to foreclosure, and this will affect their scores for seven years. Or they can do a deed in lieu of foreclosure. With a deed in lieu, you voluntarily give your home to the lender in exchange for the cancellation of your loan. This, too, can create a negative mark on your credit history.
How long does a deed in lieu take?
If you've already stopped making payments and are waiting for foreclosure, the financial difference might not matter. But DIL gets things in motion so that you can hopefully buy again or rebuild your credit more quickly. It's wise to expect around 90-days for processing time.
Related Question Answers
Do I have to pay taxes on a deed in lieu?
Generally, homeowners using short sales or deeds in lieu are required to pay tax on the amount of the forgiven debt—but not if they qualify for the Qualified Principal Residence Indebtedness (QPRI) exclusion. The QPRI exclusion was first introduced in the Mortgage Forgiveness Debt Relief Act of 2007, and I.R.C.Is it better to short sale or deed in lieu?
Like a deed in lieu of foreclosure, a short sale is also a negotiated remedy between a defaulting homeowner and the lender. The borrower sells the house for an amount less than the outstanding mortgage debt, and the lender agrees to accept this lesser amount and cancel the foreclosure.When should you walk away from your mortgage?
Foreclosed borrowers can expect to wait anywhere between two and five years before they are eligible to get a new mortgage. Borrowers who voluntarily walk away may have to wait twice as long. Fannie Mae recently announced their plans to lock strategic defaulters out of new loans for seven years!Is deed in lieu a good idea?
Although settling the mortgage for less than the full balance owed will still hurt your credit, the damage may not be quite as bad. And while a deed in lieu arrangement will hamper your ability to get another home loan for up to four years, that's better than the seven-year wait that applies to most foreclosures.Can a bank refuse a deed in lieu of foreclosure?
Banks are under no obligation to accept a deed in lieu of foreclosure. Here are a few reasons why a bank might refuse a deed in lieu: Or, a second lender might accept a deed in lieu if the first loan is current and the property is worth more than the sum of its encumbrances.How long after a deed in lieu can I buy a house?
An FHA-approved lender may approve a borrower for a loan three years after a deed-in-lieu. FHA requires a minimum down payment of 3.5 percent for borrower with at least a 580 credit score.What is a friendly foreclosure?
A friendly foreclosure, by definition, is another term for a deed-in-lieu of foreclosure. This is a process where the homeowner or property owner voluntarily returns the property to the lender, allowing both to avoid the long and drawn-out process of a foreclosure.What does it mean deed in lieu of foreclosure?
A deed in lieu of foreclosure is a deed instrument in which a mortgagor (i.e. the borrower) conveys all interest in a real property to the mortgagee (i.e. the lender) to satisfy a loan that is in default and avoid foreclosure proceedings.Do you get a deed when you pay off your house?
When you pay off your loan and you have a mortgage, the lender will send you, or the local recorder of deeds or office that handles the filing of real estate documents, a release of mortgage. With a deed of trust you temporarily hand over control of the title to your property to the lender for security purposes.Can a lien holder foreclose on a property?
Legally, all property lien holders can force a property into foreclosure, regardless of their seniority on property titles. It's much harder for a second mortgage lender to foreclose, however. That's because senior lien holders are paid first, with junior lien holders sometimes left with no sale proceeds to claim.How bad is a short sale on your credit?
The term "short sale" does not appear in a credit report. If your payments were never late, the mortgage will remain on your credit report seven years from the date it was reported settled or paid. Failing to pay your mortgage debt in full will always have a very negative affect on your credit scores.How long does a short sale stay on your record?
seven years
How bad is foreclosure?
According to FICO, if your credit score is 680, a foreclosure will drop your credit score on average by 85 to 105 points. If your credit score is excellent at 780, a foreclosure will drop your score by 140 to 160 points. In other words, the higher your credit score the more it will get smashed!What does it mean to foreclose on a lien?
A foreclosure lien, or mortgage lien, is a type of legal proceeding initiated by a lender against the borrower (usually the homeowner). A lien would allow the lending institution to obtain legal possession of the person's property. This is usually done in connection with defaulted mortgage payments.How can I settle my second mortgage for less?
How to Settle a Second Mortgage for Less- Contact the lender to discuss the debt. Begin the settlement process by expressing an interest in paying the debt.
- Make an offer. If you start your offer low, expect the lender to counteroffer.
- Remind the lender you know your rights.
- Put any agreement in writing.
- References (3)
- Resources (1)
- About the Author.