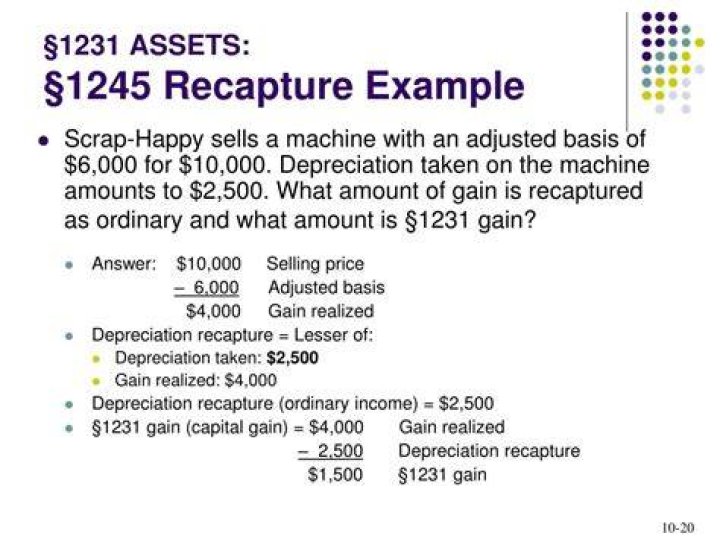
Depreciation recapture is the gain realized by the sale of depreciable capital property that must be reported as ordinary income for tax purposes. Depreciation recapture is assessed when the sale price of an asset exceeds the tax basis or adjusted cost basis..
Thereof, is there depreciation recapture on personal property?
All personal property, whether tangible or intangible, is subject to depreciation recapture under Section 1245.
Also Know, how do you report depreciation recapture? It applies to the portion of the gain attributable to the depreciation deductions you've already taken. You report depreciation recapture on IRS Form 4797, Sales of Business Property.
Secondly, can you avoid depreciation recapture?
There are only two ways to avoid depreciation recapture taxes. You can NOT avoid depreciation recapture taxes by making the property your principal residence. You will still owe the taxes when you sell the property. Depreciation is recaptured at the time of sale, whether you took the depreciation or not.
How is depreciation recapture taxed?
Depreciation recapture is the portion of the gain attributable to the depreciation deductions previously allowed during the period the taxpayer owned the property. The depreciation recapture rate on this portion of the gain is 25%. The remaining $3 million gain would be taxed at the 20% capital gain rate.
Related Question Answers
Do you recapture depreciation on 1250 property?
Gain from selling Sec 1250 property (real estate) is subject to recapture – the excess of the actual amount of depreciation previously claimed for the property over the amount of depreciation that would have been allowable under the straight-line method, limited to the gain on the sale, is taxed as ordinary income.Is there depreciation recapture on land improvements?
Land improvements such as sidewalks, fences and landscaping are depreciated on an accelerated basis and can give rise to additional depreciation or recapture if the taxpayer does not acquire replacement property with an amount of section 1250 property equal to the additional depreciation.What happens if you don't depreciate rental property?
Skipping DepreciationYou cannot apply the expense deductions from a passive activity against your regular income. If your total rental expenses exceed your rental income, the annual depreciation of your home does nothing to reduce your taxes.What type of property are land improvements?
Examples of land improvements include sidewalks, roads, canals, waterways, drainage facilities, sewers, wharves and docks, bridges, fences, landscaping, shrubbery, and radio and television towers. Note that some activity asset classes also include land improvements such as asset class 57.1 of Rev.What happens to depreciation when you sell an asset?
Depreciation spreads the item's cost out over its life, simulating its gradual deterioration or obsolescence. When you sell an a depreciated asset, the proceeds could be taxable if you sell it for more than its depreciated value.Should I depreciate my rental property?
Unfortunately, the IRS rules require you to include accumulated depreciation for your property when it is sold, even if you did not take the expense in prior years. In most cases, it's of greater benefit to claim the depreciation expense while the property is being rented to reduce your taxable income each year.How do you calculate property depreciation?
It's a simple math problem to calculate depreciation. You take the value of the item (or the property itself as you will learn below) and divide its value by the number of years in its reasonable lifespan. Then you have the amount you can write off on your taxes as an expense each year.How long can you claim depreciation on an investment property?
Capital works deductionsThis depreciation is spread over 40 years - the length of time the ATO says a building lasts before it needs replacing. For instance, on a new building that cost $200,000 to build, you could make a $5,000 tax claim each year for 40 years (i.e. 2.5% per year).What is the depreciation recapture tax rate for 2019?
Depreciation recapture on non-real estate property is taxed at the taxpayer's ordinary income tax rate, rather than the more favorable capital gains tax rate. Depreciation recapture on gains specific to real estate property, referred to as unrecaptured section 1250 gains, are capped at a maximum of 25% for 2019.How do you avoid depreciation?
Avoid depreciation recapture by selling the asset for a price that is below the book value. For example, selling a computer with a book value of $800 for $799 or lower results in no profit being realized, which eliminates any depreciation recapture. Exchange the asset for another similar asset.What is the purpose of depreciation recapture?
Depreciation recapture is the USA Internal Revenue Service (IRS) procedure for collecting income tax on a gain realized by a taxpayer when the taxpayer disposes of an asset that had previously provided an offset to ordinary income for the taxpayer through depreciation.What happens when rental property is fully depreciated?
It depends but in this instance, the residential rental property will be considered fully depreciated after 27.5 year. According to the IRS, You must stop depreciating property when the total of your yearly depreciation deductions equals your cost or other basis of your property.Do you have to recapture Section 179 depreciation?
You may have to recapture the section 179 deduction if, in any year during the property's recovery period, the percentage of business use drops to 50% or less. Instead, use the rules for recapturing depreciation explained in chapter 3 of Pub. 544 under Section 1245 Property.Why is depreciation an expense?
Since the asset is part of normal business operations, depreciation is considered an operating expense. The reason is that cash was expended during the acquisition of the underlying fixed asset; there is no further need to expend cash as part of the depreciation process, unless it is expended to upgrade the asset.How much can you depreciate a rental property?
Your depreciation expense that you take each year against rental income would be $125,000 divided by the IRS allowed 27.5 years of useful life (residential real estate) for a depreciation expense each year of $4,545.How is depreciation defined?
In accounting terms, depreciation is defined as the reduction of recorded cost of a fixed asset in a systematic manner until the value of the asset becomes zero or negligible. An example of fixed assets are buildings, furniture, office equipment, machinery etc..Can I claim depreciation on my rental property?
Residential Rental Properties: The New Depreciation Rules. Since then, investors in residential rental properties have not been able to claim decline in value deductions in relation to the acquisition of second-hand assets or assets which were previously used for private purposes.What can offset depreciation recapture?
Depreciation recapture on real property is nothing more than a specially taxed type of capital gain. As such, it can be offset by capital losses. Recapture basically means that you must take the prior depreciation deductions back into income. Recapture occurs when a property is sold.What is the difference between Schedule D and Form 4797?
To oversimplify, Schedule D is for reporting capital gains and losses on investment property, such as stocks, bonds, and mutual funds. Form 4797 is for reporting the sale of capital assets, such as equipment your business used to produce goods or sell services to the public. 
 Emily Cortez